




Have you ever wondered how businesses manage the value of their technology over time? Understanding IT asset depreciation is key to managing them. It helps to keep your organization's financials accurate and resources well-distributed. Depreciation helps you allocate the cost of IT assets over their useful life so you can plan and manage them effectively.
In this article, we will explore what depreciation of IT assets means and how it fits in the bigger picture of an IT Asset Management (ITAM) strategy. We'll also cover calculation methods, how to choose the right one for each asset, and the importance of tracking these changes.
Depreciation of IT assets is the accounting method that spreads the cost of technology such as laptops, servers, and networking equipment over its useful life, so each year's financial statements record the portion of value the asset consumed in that period. This practice is vital for accurately reflecting the financial status of a company.
An asset, in this context, is any resource owned by a business that is expected to provide future economic benefits. Examples of IT assets include computers, software, servers, and networking equipment. The depreciation of IT assets specifically focuses on how these resources lose value over time due to factors like wear and tear, technological obsolescence, and market demand.
Understanding the depreciation of IT assets is crucial for effective Financial Management. IT assets can be costly, and failing to account for their depreciation accurately can lead to issues in financial planning and asset lifecycle management. Depreciating IT assets helps organizations in the following ways:
For example, a server purchased for $20,000 won’t retain the same value over five years. Tracking depreciation will allow you to record its decline in value, helping you plan when to replace it or what residual value you can still gain if it’s sold.
In IT Asset Management, depreciation applies mainly to fixed assets: long-term, tangible hardware such as servers, desktops and laptops, networking equipment, and data center infrastructure like power supplies, cooling systems, and racks. These assets wear out and lose value to newer technology, so they sit at the center of depreciation schedules among all the types of IT assets an organization manages.
Intangible assets, such as software licenses, patents, and intellectual property, follow the same logic of allocating cost over useful life, although accountants call it amortization. For U.S. tax purposes, the IRS allows businesses to depreciate off-the-shelf software over 36 months using the straight-line method.
Understanding depreciation is essential for managing IT assets effectively. It involves more than just accounting for the passage of time; several factors influence how assets lose value over their lifecycle.
Let's break down some of the most important concepts to keep in mind when dealing with asset depreciation.
The useful life of an IT asset is the expected period during which it will continue to deliver value to the business. This timeframe can vary significantly depending on the type of asset, its purpose, and external factors such as industry changes. For example:
Tracking the useful life of each asset helps in planning for replacements, upgrades, or reassigning its function to less critical roles within the company.
These are ranges common in business practice. Tax jurisdictions may apply different schedules: the U.S. IRS MACRS depreciation system, for example, classifies computers as 5-year property.
This is the estimated resale or scrap value of an asset after its useful life ends. It represents the portion of the initial cost that cannot be depreciated. Accurately estimating salvage value is important for calculating depreciation because it determines the total amount that will be written off over time.
For example, if a laptop is purchased for $1,200 and is expected to have a resale value of $200 after four years, its depreciable cost would be $1,000. This value is spread across the four years to calculate annual depreciation. Underestimating or overestimating the salvage value can lead to inaccurate financial records.
While they are often used interchangeably, lifespan and useful life represent different concepts. Lifespan refers to the total time an asset remains functional, regardless of whether it still holds economic value. Useful life, on the other hand, is the period during which the asset contributes to the company's revenue or productivity.
For example, a company may continue to use a five-year-old desktop computer even though its useful life has technically ended. The computer may still be functional, but it no longer meets the performance requirements of modern business applications, leading to a need for replacement.
A depreciation schedule is a detailed plan that outlines how an asset's value decreases over time. It typically includes the asset's purchase date, cost, useful life, salvage value, and the method of depreciation used.
This schedule helps businesses track their assets' depreciation for accounting and tax purposes. With an accurate depreciation schedule, companies can ensure they correctly report their financial status and make informed decisions about Asset Management.
There are several methods for calculating the depreciation of IT assets, each with its advantages and disadvantages. The most common types include:
The straight-line method spreads the cost of an asset evenly over its useful life, meaning the same amount of depreciation is charged each year. This method is widely used because it is simple and provides a steady expense over time, making it easy to predict and budget for asset depreciation.
Formula:
Annual depreciation expense = (Cost of Asset − Salvage Value) ÷ Useful Life
Example: Suppose you buy a server for $10,000, and it has a useful life of 5 years with a salvage value of $1,000. The annual depreciation expense would be:
(10,000 − 1,000) ÷ 5 = $1,800
This accelerated depreciation method allows you to write off larger amounts of the asset's cost in the earlier years of its useful life. It reflects the fact that many IT assets (like computers and networking equipment) lose value quickly after purchase. The most common variant of this method is the double declining balance (DDB) method.
Formula:
Depreciation expense = 2 × Straight-line depreciation rate × Book value at beginning of year
Example: If the server costs $10,000, has a useful life of 5 years, and no salvage value, you calculate the straight-line depreciation rate first:
Straight-line rate = 1 ÷ 5 = 0.20
Now, double that rate (0.40 or 40%) for the DDB method. In the first year, the depreciation expense would be:
10,000 × 0.40 = $4,000
In the second year, you apply the 40% to the remaining value:
(10,000 − 4,000) × 0.40 = $2,400
The expenses get smaller each year, reflecting the rapid initial loss of value.
This method bases depreciation on how much the asset is used rather than on time. It’s ideal for assets like printers, vehicles, or machinery that wear down based on usage. To calculate this, you need to estimate the total number of units the asset can produce or its expected output over its lifetime.
Formula:
Depreciation expense per unit = (Cost of Asset − Salvage Value) ÷ Total estimated units produced
Depreciation expense = Depreciation expense per unit × Units produced in period
Example: If you have a $10,000 server expected to handle 50,000 work cycles over its life and has no salvage value, the depreciation per cycle is:
(10,000 − 0) ÷ 50,000 = $0.20
If it processes 12,000 cycles in the first year, the depreciation expense is:
0.20 × 12,000 = $2,400
This method adjusts based on actual usage, making it more flexible for fluctuating workloads.
This is another accelerated depreciation method where more depreciation is recorded in the early years of an asset's life. The sum-of-years-digits (SYD) method uses a fractional approach to calculate depreciation.
Formula:
Depreciation expense = (Remaining useful life ÷ Sum of years) × (Cost of Asset − Salvage Value)
Example: If the server costs $10,000 with a 5-year life and no salvage value, the sum of the years is 15. In the first year:
Depreciation for Year 1 = (5 ÷ 15) × 10,000 = $3,333
In the second year:
Depreciation for Year 2 = (4 ÷ 15) × 10,000 = $2,667
This method assigns more depreciation in the earlier years when the asset is more productive.
Selecting the best depreciation method depends on the type of asset and how it is used within your IT infrastructure. Here are some tips for choosing the right method:
The point of using these depreciation methods is to calculate the accumulated depreciation, which is the total depreciation an asset has incurred over its useful life. This value is essential for determining the book value of the asset, which is its original purchase cost minus the accumulated depreciation.
Knowing the book value helps businesses understand how much an asset is worth on their financial statements, aiding in budgeting, asset replacement planning, and tax reporting.
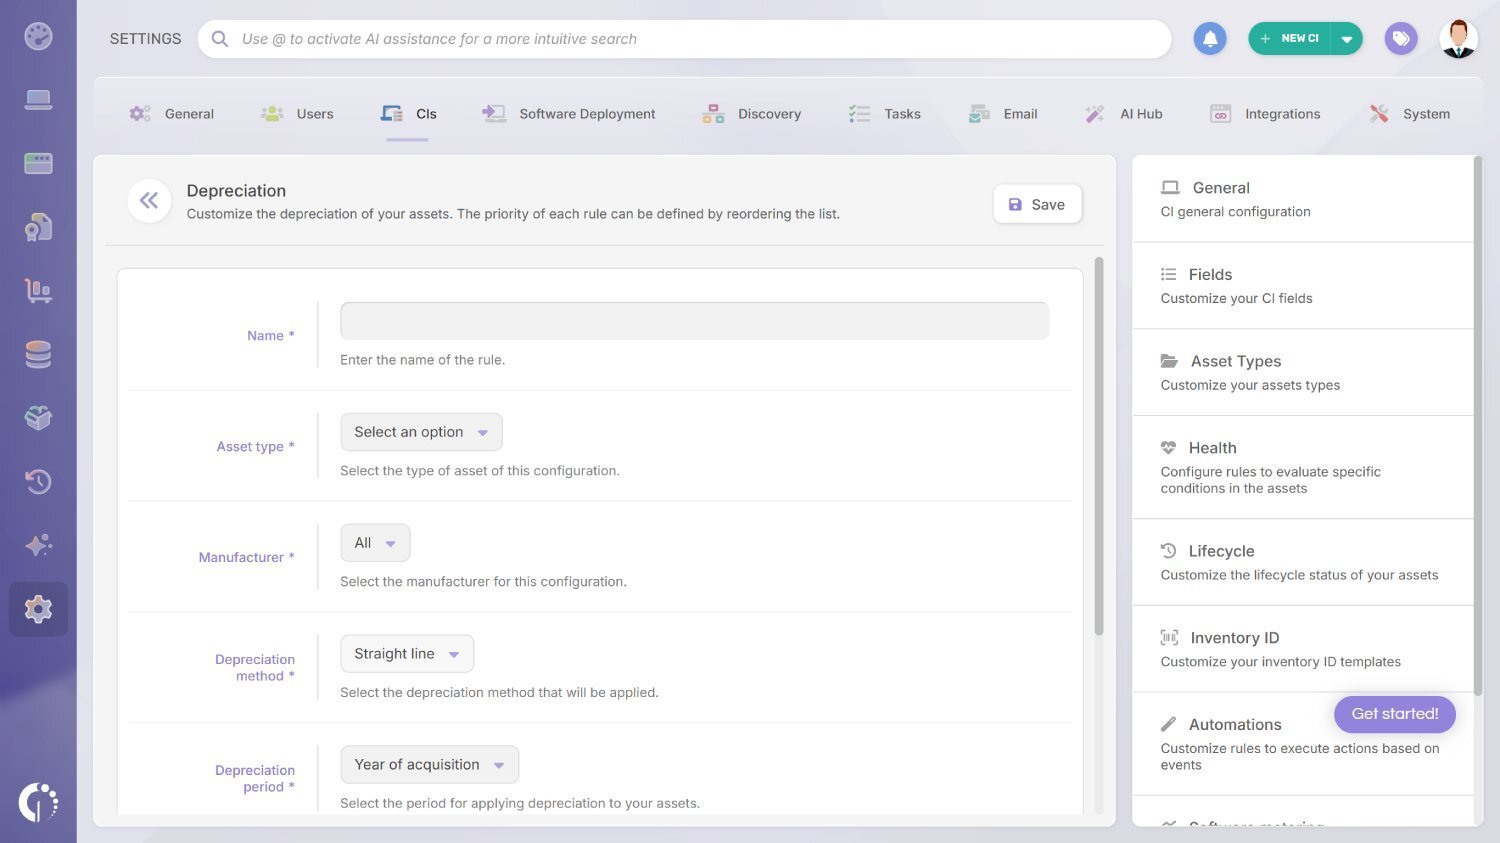
Managing IT asset depreciation manually introduces errors and consumes time that IT teams can't afford. This is especially true when you have dozens or hundreds of assets with different types, ages, and depreciation methods. InvGate Asset Management eliminates that overhead. It automates the full depreciation lifecycle, from rule configuration to value updates, so financial records stay accurate without manual intervention.
With InvGate Asset Management's automated depreciation functionality, you can:
Setting up the rules takes a few minutes, and the walkthrough on how to compute depreciation of equipment automatically covers every step, from the first rule to the value alerts.
Depreciation data also feeds the Financial Planning & Refresh dashboard, one of the features announced at ENVISION'26. This predefined dashboard brings together the residual value of the hardware fleet, accumulated depreciation, refresh spend, and chargeback by cost center, while two Smart Tags flag the devices that should be decommissioned or have already passed their retirement criteria.
Because it reads the acquisition cost, current value, warranty, and End-of-Support data the platform already holds, the dashboard answers Finance's questions without exports or spreadsheets, alongside the rest of InvGate Asset Management's IT budgeting and asset depreciation capabilities.
Note: InvGate Asset Management currently supports straight-line depreciation. Other methods described in this article, including declining balance, units of production, and sum-of-years-digits, are not available in the platform.
IT asset depreciation is a unique case compared to other types of assets. The factors influencing IT asset depreciation are quite specific and complex.
Let's explore how these elements come into play:
Rapid changes in technology often mean that IT equipment becomes obsolete before it physically deteriorates. Companies should factor this into their depreciation schedules to reflect the fast pace of innovation.
Moore's Law, first described by Gordon Moore in 1965 and revised in 1975, holds that the number of transistors on a microchip doubles approximately every two years. This leads to exponential increases in computing power while reducing costs. As a result, IT hardware loses relative value fast. Equipment that was top-of-the-line two years ago can be outperformed by significantly cheaper models today.
The lifespan of software also directly affects hardware depreciation. As software requirements increase, older hardware may no longer be able to run the latest versions effectively.
Additionally, the value of IT equipment often drops sharply once the manufacturer ends support for that model. This is particularly true for networking equipment, servers, and specialized hardware where ongoing security updates and technical support are critical.
For these reasons, many organizations apply accelerated depreciation methods to IT equipment. The rate of value loss in the first years is typically much higher than for traditional fixed assets.
Regular maintenance can extend the life of IT assets, delaying the need for replacement. This includes cleaning, software updates, and component checks.
Upgrades also play a role. Some IT assets, especially in enterprise environments, are designed with modularity in mind. Upgrading specific components (like network cards in a server) can be more cost-effective than replacing the entire system.
The cost of maintenance and upgrades should always be weighed against the extended lifespan and improved performance they provide. In some cases, the cost of keeping older equipment operational exceeds the benefit. Depreciation data is exactly what makes that decision quantifiable.
Heavy use accelerates depreciation. If an IT asset is running 24/7 or handling resource-intensive tasks, it will lose value faster than equipment that is used sporadically. IT equipment in high-usage scenarios often requires more robust cooling solutions. The depreciation of these cooling systems should also be considered alongside the IT assets themselves.
Businesses should regularly evaluate how their assets are being used to determine whether their depreciation calculations remain accurate.
As mentioned earlier, salvage value is a key element in calculating depreciation. IT equipment often experiences a steep decline in resale value. This is a direct consequence of the pace of hardware innovation described above.
In certain cases, resale value may drop sharply if the market is flooded with similar technology. Conversely, some specialized or high-demand items may retain their value longer than anticipated. Regularly reassessing salvage value assumptions ensures depreciation schedules stay aligned with real-world market conditions.
Depreciation of IT assets turns the cost of every laptop, server, and switch into a figure Finance can plan around, and choosing the right method and useful life keeps that figure accurate. To track it automatically, start a free trial of InvGate Asset Management or talk to Sales to see how it fits your fleet.
Depreciation is the accounting method used to allocate the cost of an IT asset over its useful life, reflecting wear and tear, technological obsolescence, and market-driven value loss. It lets organizations spread a purchase across the years the asset is in use and know its current book value at any time.
The most common method is straight-line depreciation: subtract the salvage value from the asset's cost, then divide by the useful life. For hardware that loses value quickly, accelerated methods like declining balance or sum-of-years-digits are typically more accurate.
Laptops typically depreciate over 3 to 4 years and desktops over 4 to 5 years in business practice. Under U.S. tax rules (MACRS), computers and peripheral equipment are 5-year property, while office furniture is 7-year property, so computer equipment follows the 5-year schedule. Many U.S. businesses can also deduct the full cost in the first year through the Section 179 deduction or the special depreciation allowance, which the One Big Beautiful Bill Act restored to 100% for qualifying property acquired after January 19, 2025.
It depends on how the asset loses value. Straight-line works well for predictable hardware with stable usage. Accelerated methods (declining balance, SYD) fit IT equipment that drops in value fast due to technological obsolescence.
In financial accounting, software is amortized, which allocates its cost over the license's useful life the same way depreciation does for hardware. For U.S. tax purposes, IRS Publication 946 sets a 36-month (3-year) straight-line period for off-the-shelf software that qualifies for depreciation. Subscription-based software is typically expensed as it is consumed.
Under the straight-line method, the annual depreciation rate is 1 divided by the asset's useful life. Equipment depreciated over 3 years loses about 33% of its depreciable cost each year, over 4 years 25%, and over 5 years 20%. Accelerated methods such as double declining balance apply twice that rate to the remaining book value, so the yearly expense starts higher and decreases over time.

